
The $20,000 instant asset write-off has been made permanent for small businesses from 1 July 2026. The change was announced during the 2026 Budget and became law on Wednesday, 26 August, with the assent of the Treasury Laws Amendment (Tax Reform No. 2) Bill 2026. In previous years, the concession was uncertain and relied on yearly extensions to the scheme.
What is the instant asset write-off?
The measure allows small businesses to immediately deduct the cost of eligible depreciating assets against a business’s taxable income for the income year that the asset is first used for a taxable purpose. To be eligible, businesses must have an aggregated annual turnover less than $10 million. The immediate deduction is aimed to improve cash flow, encourage investment and business efficiency, and reduce compliance burden for small businesses.
How does the write-off work?
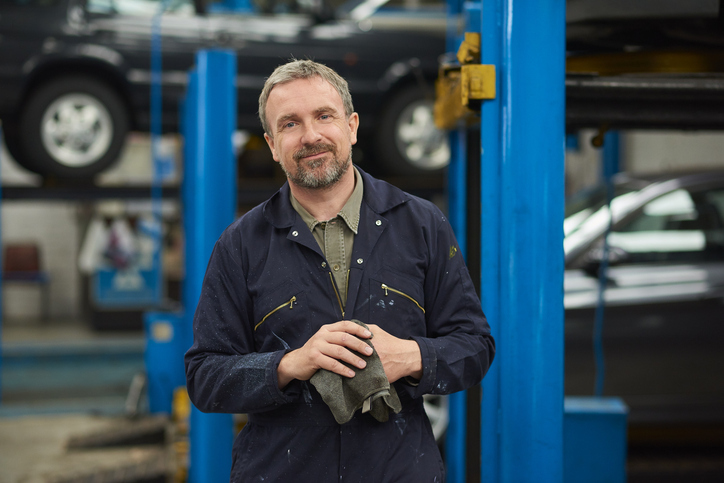
Suppose that a panel beater decides to upgrade several pieces of equipment:
- Installation and supply of new signage totalling $8,600,
- An industrial car hoist (including installation) for $9,700, and
- A new office computer costing $1,800.
Each asset costs less than $20,000 and is installed ready for use in the business. The $20,000 limit is per asset, not aggregated across all assets. Rather than depreciating these assets over several years, the panel beater can choose to claim an immediate deduction.
The immediate write-off would total $20,100 and reduce the total tax payable by $5,025 (if the small business was operating in a company structure and eligible for the 25% tax rate). This immediate deduction assists with cash flow and provides an opportunity for further investment. The panel beater could invest in more equipment in the next year or fund the previous purchase, improving productivity and growth.
Things to keep in mind
The concession may not be appropriate in every situation. In some cases, broader tax planning considerations, current profitability, or future expected income may influence the best approach. The instant write-off is opt-in, not mandated.
Businesses should consider eligibility requirements and limitations, including:
- Whether they qualify as a small business entity (less than $10 million aggregated turnover).
- Whether the asset is a depreciating asset and is used for a taxable purpose.
- The timing of when the asset is first used or installed ready for use.
- The portion of the asset that is used for taxable purposes. Usage must be apportioned so that only the business use is deducted.
- Whether there is sufficient taxable income to deduct the purchases against.
The write off reduces your taxable income, not tax payable directly. This means that the tax benefit from writing off an asset is less than its cost price. A $10,000 asset would reduce tax payable by $2,500 (if the taxpayer’s tax rate is 25%). Hence, the tax concession should be a secondary consideration to the business’s overall commercial strategy.
Final thoughts
The permanent $20,000 instant asset write-off is a welcome development for Australia's small business sector. By providing certainty and allowing faster access to tax deductions on eligible equipment purchases, the measure provides business owners with an opportunity to invest in the tools and technology they need to operate and grow.
The change is another reminder that reviewing planned capital expenditure as part of tax planning with your advisor can deliver meaningful tax and cash flow benefits.
